During a meeting with an aluminum-extrusion client, the general manager asked me, “We do not export directly to the EU. Does CBAM have anything to do with us?”
I replied, “Who is your customer? And who is your customer’s customer?” The supply chain led to a German automaker. That question helped reveal the downstream market, but it did not establish whether this shipment fell within CBAM.
As SSBTi’s circular-economy partner, I care about Taiwanese companies’ ability to manage their own carbon data. These are my practical observations and recommendations, not an official association statement or a regulatory determination for particular goods.
A company that does not export directly to the EU may still receive a customer’s data request. But being asked for data and becoming a legally responsible CBAM declarant must be distinguished.
Establish the goods and declarant before discussing supply-chain pressure
The European Commission’s definitive-regime guidance identifies selected goods in sectors including cement, iron and steel, aluminum, fertilizers, electricity, and hydrogen. The definitive regime began on January 1, 2026. Declaration and certificate-surrender obligations depend on the relevant roles, such as EU importers or indirect customs representatives, and applicable conditions.
An automotive customer or a supply chain ending in the EU does not, by itself, make every shipment of materials, parts, and finished products subject to CBAM.
I would establish four things first: which shipment, which commodity code, who imports it, and which period applies. Then check coverage, annual thresholds, and exceptions. A plant’s total output cannot substitute for the importer’s position under the system.
Timing must also be separated. The EU’s declaration information explains that the first annual declaration and corresponding certificate surrender in 2027 concern 2026 imports. The start of the definitive regime, importation, data preparation, and fulfillment of annual obligations do not all happen on the same day.
Customer requests can travel upstream without automatically becoming your statutory obligation
Once the legal scope is established, return to the general manager’s real concern: will the customer ask us for data?
Possibly. A buyer seeking emissions information for covered goods may need supplier support. Customers may also collect information upstream for their own procurement policies or other disclosure requirements. Each request deserves attention, but its purpose and acceptance criteria should not be conflated.
I would ask the customer to make the request actionable:
- Is it for a CBAM declaration, a product carbon footprint, or corporate disclosure?
- Which product, plant, and data period does it concern?
- Which fields, calculation methods, and evidence are required? Is independent verification needed?
- Who may use the data, who receives it, how is confidentiality handled, and when will it be accepted?
First ask who wants the data, what it is for, and how it will be accepted. An email bearing the letters ESG is not a reason to purchase every certification at once.
Whether a customer passes costs on, and how data-preparation or verification costs are shared, depends on actual orders, quotations, and contracts. Commercial relationships may be affected, but that does not mean every upstream company inevitably bears the same CBAM charge.
Default values are a prescribed method, not a uniform fine for missing data
The EU’s explanation of actual and default values permits both routes under the rules. When actual emissions are chosen, the third-country producer must supply the corresponding verified emissions data. That is very different from entering a low number and waiting for someone to believe it.
Defaults should not be described as the EU making an ad hoc choice of the highest-emitting countries to set a company’s price whenever it lacks data. Which value applies, to which goods, country, or production route, and whether it includes an applicable mark-up all require checking the rules and version.
As checked on November 3, 2026, the Commission’s legislation and guidance page lists the correction to default values under Regulation 2026/1740 and a corrected reference spreadsheet published that August. It also distinguishes the legally binding regulations from the spreadsheet provided for information.
The data version must travel with the number. A value that already includes a mark-up must not be multiplied again without checking. Rules for different goods should not be compressed into one percentage. Whether an actual value is above or below a default requires comparison on matching terms; measurement cannot be promised to make every case cheaper.
I want to retain the phrase “carbon-data sovereignty,” but make its meaning more concrete: knowing where data comes from, what it is fit for, who can verify it, and who must recalculate when rules change.
A cost percentage needs a complete, reproducible set of assumptions
The earlier essay used an aluminum example to state 3.83%, then projected about 6% in 2028. Those figures are no longer retained as industry-wide costs or buyer quotations.
To reconstruct a CBAM cost, I would require at least the following in the spreadsheet:
| Input | Questions that cannot be omitted |
|---|---|
| Goods and quantities | Do the commodity code, import period, and quantity correspond? |
| Emissions value | Actual or default, under which version and scope? |
| Free-allocation adjustment | Which current CBAM benchmarks and calculation rules apply? |
| Carbon price already paid | Are deduction conditions met, and how are evidence and adjustments handled? |
| Certificates and currency | Which period’s unit price and exchange rate, from which sources? |
| Comparison denominator | Which aluminum-price period, specification, and transaction terms? |
The Commission’s same legislation page separately lists CBAM benchmarks under Regulation 2025/2620. Finding an ETS benchmark in old material is not enough to apply it to a new year’s liability without checking the period and method.
Even a calculated amount’s share of the selling price does not mean profits will fall by the same proportion. Who ultimately bears it also depends on negotiation, contracts, product mix, and actual costs. When information is missing, retaining the gaps helps a company decide more than an apparently precise percentage does.
Underlying records can be reused without different systems accepting the same answer
Organizing data can reduce duplication. Energy bills, material use, output, and purchasing records may support more than one task. But allocation, calculation, verification, and disclosure must still be checked separately.
Several names often appearing together also need to be distinguished:
- SBTi assesses whether emissions targets meet the relevant requirements. It does not endorse every product’s actual emissions.
- CDP provides environmental disclosure and scoring processes, not a universal product certification.
- EcoVadis ratings and medals concern the assessed company’s sustainability management system. They do not directly prove a product’s CBAM compliance.
- ISCC has different schemes and supply-chain traceability requirements. Check the selected scheme and certification scope; its name alone does not establish compliance with another regulation.
This continues the point I wanted to clarify in the EPD roadmap: ask what the receiving party needs before deciding what to deliver. A partnership with SSBTi does not mean targets have been validated by the international SBTi either.
A foreign background database is not necessarily inaccurate because it is foreign, and local data does not automatically fit because it is local. Compare technology, geography, period, methods, and traceability, rather than ranking data by nationality.
Procurement can start organizing evidence without promising a complete certification package
If I were starting today, I would begin with a particular shipment and one customer request already received.
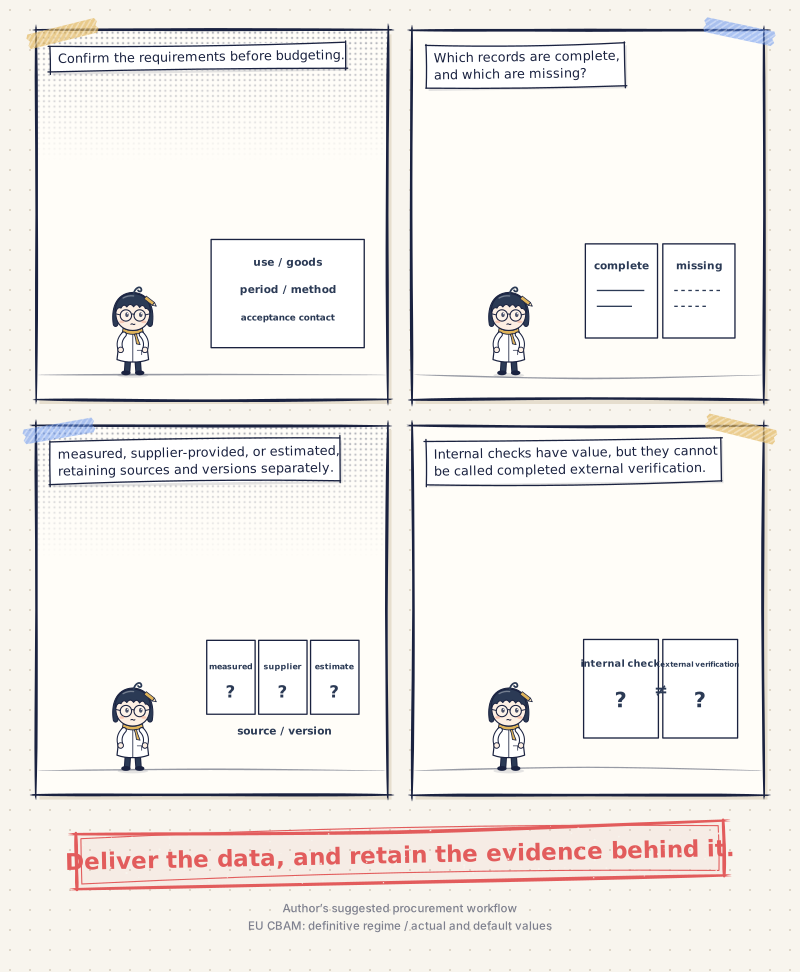
First, record the request: customer, purpose, goods, plant, period, method, deadline, and contact. Confirm the requirements before budgeting.
Second, locate the records: who holds purchasing quantities, materials, energy, output, and transport information? Which records are complete, and which are missing? Purchasing spend can help prioritize work, but without evidence it cannot establish that the top fifth of suppliers produces four-fifths of emissions.
Third, identify the data type: measured, supplier-provided, or estimated, retaining sources and versions separately. When data is missing, establish which alternatives the particular system permits. Do not decide on any industry average and declare compliance complete.
Fourth, cross-check before delivery. If documents and quantities do not reconcile, investigate. Bring in the appropriate people for professional modeling or independent verification where needed. Internal checks have value, but they cannot be called completed external verification.
These four steps are my recommendations, not SSBTi’s official universal procedure. They do not guarantee a certificate in ninety days, six months, or two years. The earlier forecast that unprepared companies would inevitably be eliminated within three years lacked sufficient support and should also be withdrawn.
I still want companies to take greater responsibility for their data. That means defining scope, finding records, explaining gaps, and being accountable for what they provide externally.
Deliver the data, and retain the evidence behind it.

💬 Comments
Loading...