As a circular-economy partner of SSBTi, I follow corporate decarbonization and often return to a practical decision: why does one company see an engineering project as worthwhile while another does not? What follows is my own analysis, not an official statement from the association or any individual scholar.
On May 12, 2026, a United Daily News report said that, a year and a half after Taiwan’s domestic carbon-credit platform opened, fixed-price trading had produced just five transactions totaling 69 tonnes. The earlier version of this essay jumped from that figure to a verdict: “Not market failure, but policy success.”
That was too quick. Low trading volume alone proves neither market failure nor the success of emissions-reduction policy. More useful questions are what kind of trading the figure covers, whose demand it represents, and how much companies actually reduced their emissions.
I still want to discuss how carbon enters business decisions. But the starting point needs to change: put each price back into its own system, then separate decision models from money in the bank.
Three carbon prices: what does each one price?
The earlier essay placed NT$300, NT$3,000–4,000, and roughly NT$2,790 side by side, calling them three prices for the same tonne of carbon. Each appears to be quoted “per tonne,” but they are not interchangeable price lists.
| Name | What the price applies to | What to establish before comparing |
|---|---|---|
| Taiwan’s carbon fee | The rate applied to chargeable emissions under the system | Is the company covered, which rate applies, and how is its liability calculated? |
| A reduction credit’s trading price | The purchase or sale of a particular credit | Do its origin, vintage, permitted use, and cancellation rules meet the need? |
| CBAM certificate price | A certificate under the EU system | Which shipment and period, and how many certificates must be surrendered? |
Taiwan’s carbon-fee rate announcement sets a general rate of NT$300 per tonne of CO₂e and preferential rates A and B of NT$50 and NT$100. Preferential treatment requires conditions such as an approved voluntary reduction plan and specified reduction targets. The collection regulations also define chargeable emissions. Multiplying every company’s total emissions by NT$300 does not establish its actual payment.
The NT$3,000–4,000 range described domestic carbon credits in that May report. It does not represent the entire international voluntary market, nor is it a current quote for every transaction.
The European Commission published a first-quarter 2026 CBAM certificate price of €75.36 per certificate. That is a price for a particular quarter, not a permanently fixed “international carbon price.” A Taiwan-dollar conversion also needs an exchange rate. The earlier figure of about NT$2,790 is retained here only as an input to the old illustrative calculation below.
Five transactions cannot settle the policy question
The platform’s fixed-price transaction count does not automatically cover off-platform deals, other trading methods, or all corporate emissions-reduction activity. Even if the count is entirely accurate, it does not explain why demand has not appeared, whether supply is sufficient, or how much improvement companies have made inside their plants.
Likewise, a carbon fee designed to encourage reductions does not make every market outcome evidence of that design’s success. An assessment needs to distinguish fee collection, emissions outcomes, business behavior, and trading rules before asking what connections the evidence supports.
The earlier interpretation that the government was prohibiting companies from “buying” was also too categorical. Articles 9 and 10 of the current collection regulations allow deductions using qualifying domestic and foreign reduction credits, subject to limits and application conditions. This does not make every credit eligible, but neither is it a complete prohibition.
A company’s own reductions, its lawful use of particular credits, and the claims it makes publicly each require separate checks. Reducing everything to a choice between “reduce your own emissions” and “buy someone else’s” obscures the conditions that matter.
A shadow carbon price can change rankings without creating cash
I support bringing future carbon risks into investment decisions. First, however, the company needs to identify the tool it is using.
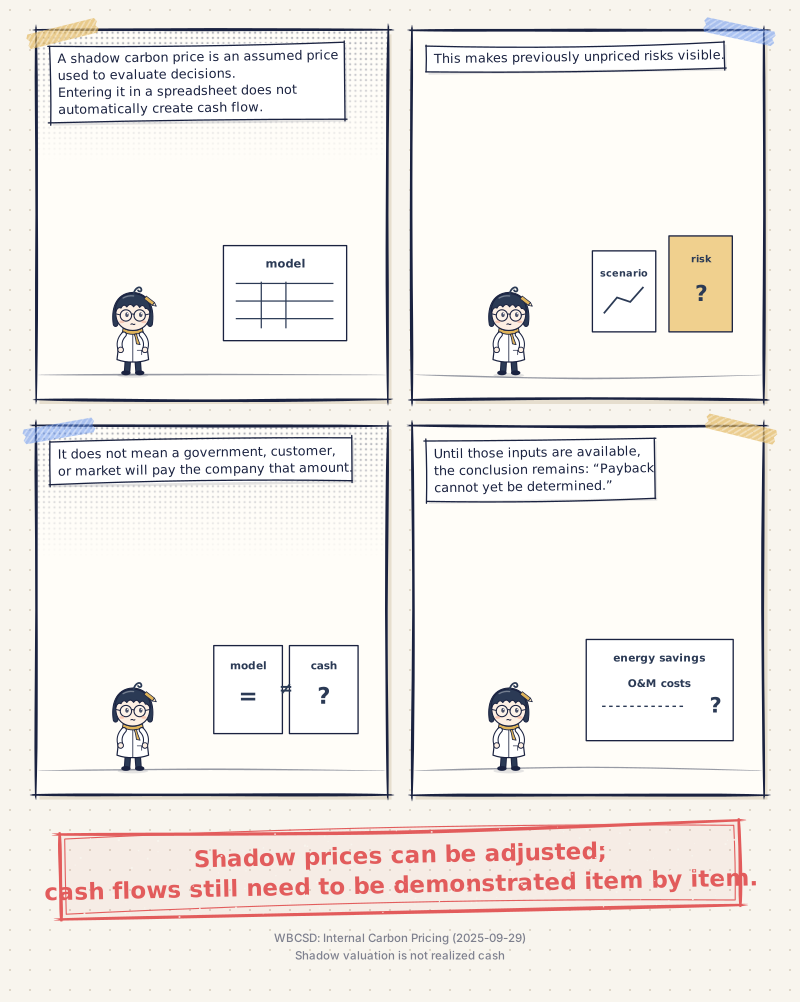
A shadow carbon price is an assumed price used to evaluate decisions. Entering it in a spreadsheet does not automatically create cash flow. WBCSD’s explanation of internal carbon pricing also distinguishes it from an internal carbon fee actually charged to business units.
A company can test different shadow prices to assess whether a high-emitting asset remains worth investing in under future scenarios. This makes previously unpriced risks visible. It does not mean a government, customer, or market will pay the company that amount.
Even when an internal fee moves budgets between departments, the company’s internal funding arrangements must be distinguished from new cash coming into the company from outside. They answer different management questions.
A shadow carbon price can therefore help rank projects. Raising the assumed price alone cannot establish a shorter actual payback period.
Split the old payback example into two tables
Keep the earlier figures: assume an investment of NT$10 million that reduces emissions by 1,000 tonnes of CO₂e each year. This is a hypothetical illustration, not verified performance from a project examined for this revision. Annual reductions are also assumed to remain constant.
| Assumed carbon price | Price × annual reduction | Investment ÷ that annual valuation |
|---|---|---|
| NT$300 per tonne | NT$300,000 per year | About 33.3 years |
| NT$2,790 per tonne | NT$2.79 million per year | About 3.58 years |
The arithmetic works, but the column headings matter. The right-hand column is only a ratio of investment to an assumed annual valuation. If the middle column is not realizable net cash flow, the right-hand column cannot be called an actual payback period.
In particular, NT$2,790 is only a comparative shadow price here. It is not the latest CBAM quote, and it does not guarantee that this plant saves that amount for every tonne it reduces. Actual CBAM obligations depend on covered goods, the import declarant, embedded product emissions, certificate quantities, and carbon prices already paid. Whole-plant reductions cannot simply be equated with the liability on a particular export shipment.
I would require a second table focused on cash: demonstrable energy savings, carbon costs lawfully avoided, and confirmed contractual benefits, less additional operating, maintenance, and other costs, without counting the same benefit twice. Until those inputs are available, the conclusion remains: “Payback cannot yet be determined.”
Net present value needs the asset’s lifetime, cash flows for each year, and a discount rate as well. A higher carbon price cannot substitute for them.
Disclosure, target validation, and verification are different things
The earlier essay called TNFD, SBTi, and CDP a “three-track third-party verification” system. That can make readers think all three certify the same emissions-reduction results.
- TNFD provides a framework for nature-related risk management and disclosure.
- SBTi target validation assesses whether science-based emissions targets meet the relevant requirements. It does not, by itself, verify every year’s actual results.
- CDP provides environmental disclosure and scoring processes. Completing a questionnaire or receiving a score does not give every product the same verification.
These can serve different management needs. When an inventory or product dataset requires independent verification, its standard, scope, and conclusion must be stated separately. A framework’s name cannot supply missing evidence. A partnership with SSBTi also does not mean certification by the international SBTi.
I still believe companies should build their own carbon-data capabilities. Those capabilities should help people distinguish evidence, rather than simply add more logos to a presentation.
Give every price in the spreadsheet its own name
Next time I discuss a decarbonization investment, I would begin with four questions. Is this a legally payable cost, a transaction price for a particular credit, or an internal assumption? Which product and period does it concern? Where does the cash actually come from? Which reductions and benefits remain unverified?
This continues a question I raised in my essay on carbon-data sovereignty: can a company control its data instead of merely accepting someone else’s conclusions? But controlling data does not entitle it to redefine legal boundaries or turn scenarios into revenue.
The approach I want to retain brings future risk into today’s decisions while keeping the discussion accountable to evidence.
Shadow prices can be adjusted; cash flows still need to be demonstrated item by item. With both made clear, the spreadsheet can begin to help a company decide.

💬 Comments
Loading...