Reading the timeline. This piece starts with experiences associated with February 23, 2020 and includes later reflection. The original publication date does not mean every outcome discussed had already happened that day.
In February 2020, the COVID-19 case numbers refreshed every day. The first thing I did every morning was open the WHO statistics page to see how much the numbers had jumped.
At that point, global cases were somewhere in the tens of thousands. I looked at the curve, and a question automatically popped into my head: when would it break one hundred thousand? When would deaths break five thousand?
This wasn’t anxiety. Okay, there was a bit of anxiety. But more than that, it was a kind of conditioned reflex. A way of thinking I’d developed during my years trading financial instruments.
Using Questions to Rehearse the Worst-Case Scenario
Back when I was trading, I did one thing every day before the market opened: I asked myself a series of questions.
What might today’s price movement look like? If it suddenly plunged 3%, what would I do? If it suddenly spiked, what would happen to my positions? What kind of movement would be “completely beyond expectation” for me? If that kind of movement occurred, how much would my current positions lose me?
These questions were not meant to settle where prices would go. Their purpose was rehearsal, examining how different scenarios would affect me.
The difference between prediction and rehearsal is enormous. Prediction says, “I think it’ll go up,” and then places a bet. Rehearsal says, “If it falls, rises, or stays flat, here’s what I’ll do in each case,” and then builds a corresponding plan.
Rehearsal can help me identify some risks in advance. Losses I did not imagine, or could not withstand, can still occur.
This habit later extended from trading into every aspect of my life. When I saw the pandemic numbers jumping, I didn’t think, “It probably won’t get too bad.” I thought, “If it gets worse than everyone expects, what will I do?”
The Thing-in-Itself Is Unknowable
I use a philosophical reminder to reflect on this habit of thinking.
The original article invoked the “unknowable thing-in-itself” to remind me that my data and interpretation are not the whole of reality. That is an association from my reading, not a proof of an investment strategy.
In Science: Conjectures and Refutations, Karl Popper discusses falsifiability: an empirical scientific claim should identify possible observations incompatible with it and specify refutation conditions in advance. Surviving rigorous tests can provide provisional support, not certainty forever. Asking what I would do if prices fell is a different task: scenario rehearsal and capacity assessment.
This logic had a profound impact on me.
Because it means: your past experience can never guarantee the future. Trading for ten years with consistently good performance doesn’t mean you truly understand the market. That performance alone does not rule out risks not yet encountered.
The capital markets are vaster than we imagine. So is the world. The data we collect is only the tip of the iceberg, our eyes are full of bias, and the way we interpret information is full of blind spots.
Every day, we are blind men feeling an elephant. The only difference is this: some people know they’re feeling an elephant, while others believe they’ve seen the whole picture.
Certainty Is Poison
In markets, I am particularly wary of certainty that has not been examined.
Fear does not necessarily make us rational, and certainty is not always wrong. My concern is that when someone stops testing assumptions, evidence conflicting with their view becomes easier to overlook.
I’ve seen too many cases like this. A trader wins for twelve straight months and begins to feel he’s grasped the market’s patterns. Then in the thirteenth month, the market makes a move he “never imagined possible,” and he loses a year’s worth of profits in a single month.
The problem isn’t the move itself. The move wasn’t especially extreme. The problem is the mindset: because of twelve months of success, he stopped asking, “What if I’m wrong?”
This is the same logic I discussed in “The Overlooked Civilizational Metric: The Risk Philosophy of Replacing ‘Goals’ with ‘Systems’”: you can’t look only at returns; you must also look at risk. Alongside returns, I need to consider how large a loss could be and what I could withstand. No particular return figure makes a strategy rock solid.
The practice I draw from falsification begins by asking what evidence would make me admit a judgment was wrong, then separately asking how I would respond to an adverse scenario. One tests judgment; the other prepares a response. They are not the same task.
What the Pandemic Taught Us
The pandemic led me to revisit some overly broad assumptions.
“Globalization brings only benefits” or “everything will grow steadily” is too broad to count as a tested claim merely by attaching the label falsification. A testable judgment needs a defined subject, period, and observation conditions. Coping with interrupted supplies or operations is a separate scenario-rehearsal question.
Looking back at the early outbreak, I want to remind myself not to skip checking a claim’s basis because its answer feels comfortable. That is a reflection on my decisions, not an investigation into every expert’s judgment or motives.
In rehearsing risks, I would separately ask: “If it really does get bad, am I prepared?” The question is inspired by falsification; it is not a completed refutation of a proposition.
In the early stages of the pandemic, I did a few things: I cut non-essential cash spending, confirmed my company’s remote-work capabilities, and assessed how long I could survive under the worst-case scenario. The original article described these preparations as seeming like an “overreaction” at the time. This passage includes hindsight: later outcomes were not already known, and the account does not compare everyone who made no such preparations.
For me, the point is to retain both questions: could my judgment be wrong, and could I withstand the outcome? They inform each other but require different checks.
Coexisting with Uncertainty
Finally, I want to discuss a more fundamental question.
Our education, our culture, our society: all of them teach us to pursue “certainty.” Get into a good school, find a stable job, buy a house, save for retirement. Every step is an attempt to eliminate future uncertainty.
The reminder I take from this approach is: do not mistake temporary confidence for the disappearance of uncertainty. What you can do is not eliminate it, but learn to coexist with it.
Coexisting with uncertainty means several things. Acknowledging that what you don’t know exceeds what you do know. Maintaining humility about your own judgments, always ready to be falsified. Building redundancy: not putting all your eggs in one basket, not building all your plans on the assumption that “everything will go smoothly.” Continually questioning, not in order to find answers, but in order to stay alert.
So it is in the market. So it is in life. So it is in the pandemic. So it is wherever black swans roam.
Losing money is losing money. Diplomas, connections, family background. They’re useless before the market. They’re useless before the black swan too. I hope that before it appears, I have seriously asked myself: “If it comes, can I hold on?”
What you can’t stop, learn to coexist with. And the starting point of coexistence is admitting: every day, we are blind men feeling an elephant. Knowing this can be a starting point for further checking and revision.
Separating the questions
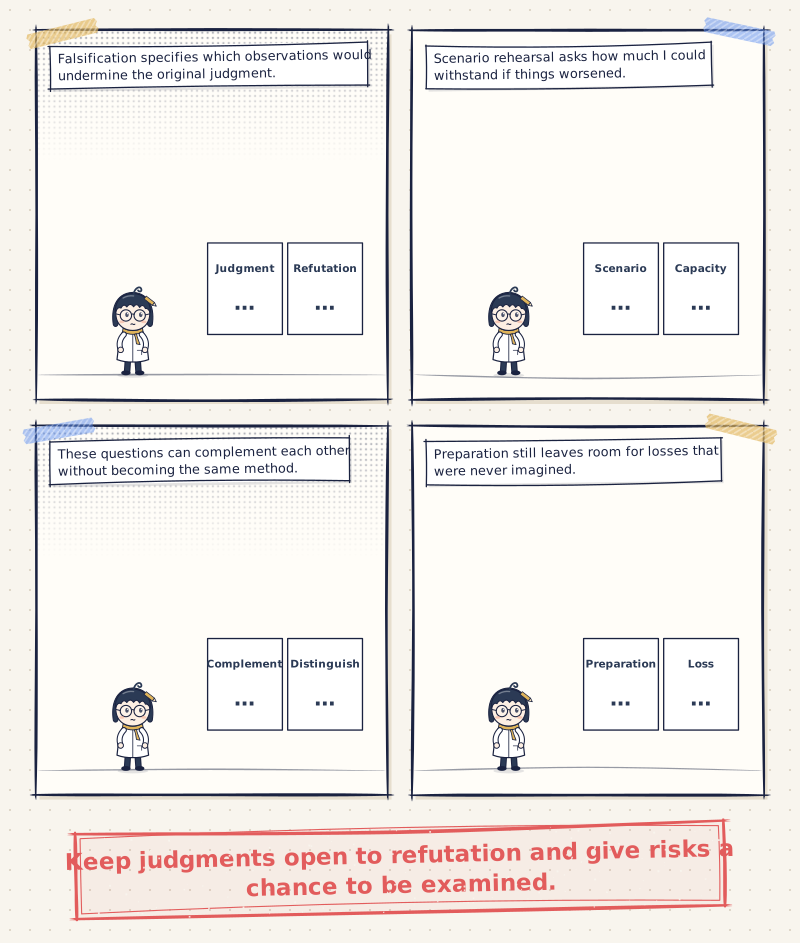
Separate refuting a judgment from rehearsing what you can withstand.
Falsification specifies which observations would undermine the original judgment.
Scenario rehearsal asks how much I could withstand if things worsened.
These questions can complement each other without becoming the same method.
Preparation still leaves room for losses that were never imagined.
Keep judgments open to refutation and give risks a chance to be examined.
Revision and source boundaries: November 5, 2026. This revision checks Popper’s original excerpt to distinguish falsifiability from scenario rehearsal, and removes an unsupported intellectual lineage and return-versus-safety comparison. Investment applications are the author’s extension. Personal trading, company preparations, and pandemic observations remain historical accounts; positions, performance, and current market conditions were not rechecked.

💬 Comments
Loading...