When markets change, the thought I want to retain is not “nobody can know anything.” It is a more practical habit: explain what supports my judgment and leave room for where it might be wrong. Humility can become a way of examining material, making decisions, and revising them.
A forecast is not a guarantee, and analysis is not pointless
A market moving differently from my expectations does not by itself establish that analysis has no value. One outcome matching expectations does not establish that I understood its causes either.
I would rather ask what the original judgment actually said. Was the direction merely similar, or were the timeframe, conditions, and possible changes also clear? If these are mixed together, it becomes easy to construct an “I knew it all along” account afterward.
The aim is not perfect precision in every judgment. It is to avoid presenting a conditional conjecture as an already settled future.
Separate direction, timeframe, and conditions
“I see promise in this direction” and “prices will rise over the next period” answer different questions. Even with the same material, different timeframes, measures, and conditions can lead to different conclusions.
For me, defining the question is more useful than rushing to take an optimistic or pessimistic position. Am I discussing long-term demand in an industry or guessing a short-term price? Was the material available at the time, or added as an explanation afterward? Which parts remain estimates without sufficient support?
These questions do not remove uncertainty. They help me identify what to examine at the next review.
Seeing promise does not make the same risk suitable for everyone
Investor.gov’s educational material includes investment timeframe and risk tolerance in its discussion. This reminds me that finding a direction worth considering and assessing how much risk a person can appropriately bear are different questions.
For myself, I want to distinguish whether the immediate issue concerns living needs, work arrangements, or a market view. If events do not follow the imagined path, which responsibilities and resources would be affected? Am I considering only a favorable outcome and leaving adverse possibilities out?
I do not intend these questions to produce a universal portfolio allocation, trading schedule, or product choice. They are a way to examine the scope of a judgment, rather than a substitute for assessing an individual situation.
Leave room for change in strategy work
Bringing this question into strategy work, I care about more than how complete a plan looks. I also care about how it will be used.
If a proposal makes sense only while an assumption holds, I want that assumption to be visible. Which material needs continued attention? When should the discussion reopen? Who will bring new information back to the team? Such arrangements can make a plan a usable and revisable tool.
I do not want to dismiss business planning or market analysis as futile. I want to remind myself that a logically clear document still has to face new material after implementation. The effort already invested should not exempt it from review.
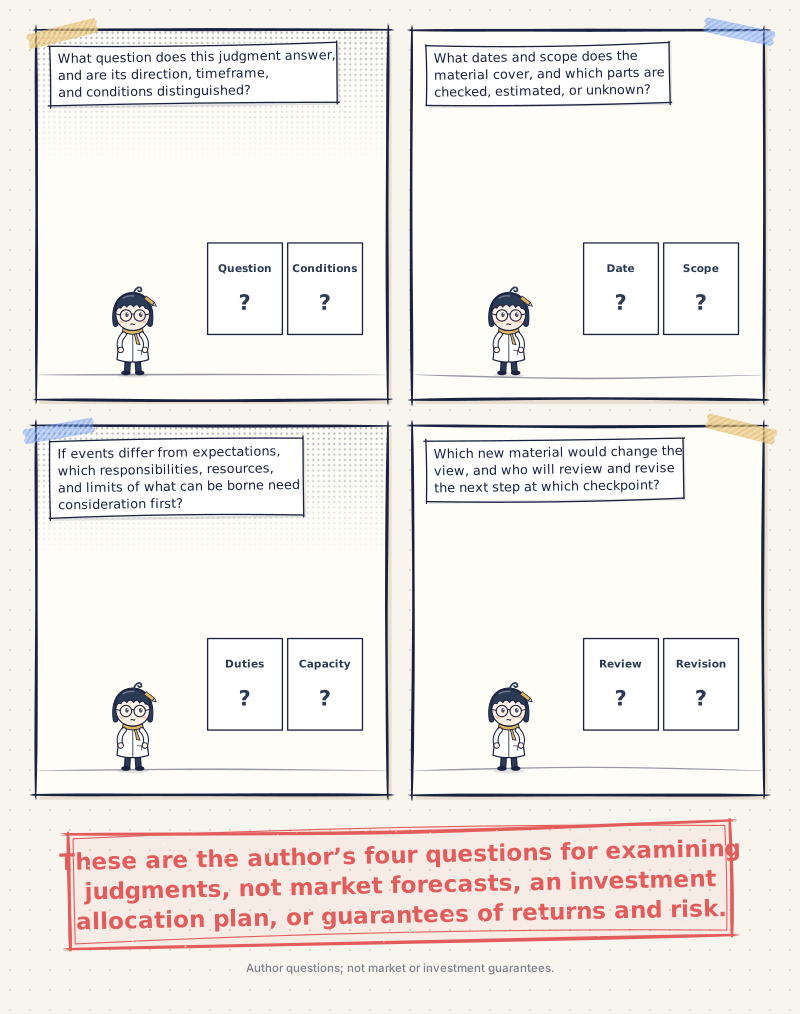
Four questions I use to examine a judgment
- What question does this judgment answer, and are its direction, timeframe, and conditions distinguished?
- What dates and scope does the material cover, and which parts are checked, estimated, or unknown?
- If events differ from expectations, which responsibilities, resources, and limits of what can be borne need consideration first?
- Which new material would change the view, and who will review and revise the next step at which checkpoint?
These are the author’s four questions for examining judgments, not market forecasts, an investment allocation plan, or guarantees of returns and risk.
Decisions can still be taken seriously under uncertainty
For me, humility does not mean saying “I don’t know” and putting responsibility aside. It means acknowledging the scope of the material and the conditions of an inference, while leaving my judgment open to examination.
At review, I want to look beyond the final outcome. Were the unknowns clear? Did I exceed what the material could support? When new information appeared, did I adjust the approach?
This preparation does not guarantee results. It helps me understand more clearly what I am relying on when action is needed, and what still requires confirmation.
Sources and revision scope: Rewritten November 4, 2026, retaining the original publication date of October 31, 2017. This is a reflection on method assembled for this revision; it does not present a 2026 retrospective as writing produced in 2017. Directly checked the necessary Investor.gov paragraphs on timeframe and risk tolerance, without adopting specific allocation, rebalancing, or product recommendations. The 2017 index highs, global asset movements, policy causation, and financial-crisis timeline were not reconstructed, so unsupported figures and dramatic episodes were removed. The former abstract’s claim of personally remaining bearish for ten years is not treated as a verified biography. Private trades, holdings, and client records were not examined. This article does not provide an individual investment plan.

💬 Comments
Loading...