Reading the timeline. This piece begins with market experiences around March 13, 2020 and includes later reflection after March 18. The original publication date does not mean subsequent events had already happened that day.
NYSE’s historical account lists four market-wide circuit-breaker triggers on March 9, 12, 16, and 18, 2020, with a 7% S&P 500 decline triggering a 15-minute trading halt. That is a different indicator from Dow point losses, and not one trigger mechanism shared by every global market.
The Dow’s index level differs across years. Dividing point losses cannot establish that a crisis was several times more severe. I retain the shock of that period here without using cross-year point losses to settle the comparison.
It all began with the global spread of COVID-19.
But what was truly frightening wasn’t the magnitude of the decline itself. What unsettled me was that I could not be certain what would happen next.
The Limits of the Frameworks I Used
As a long-term market observer, I tried to do all the “right things” during those days: read technical charts, study central bank statements, review historical comparisons. But every analytical framework I habitually used was telling me the same thing: “Your past experience doesn’t apply here.”
We’re accustomed to using the known to infer the unknown. When we see stock market crashes, our instinctive response is: “It fell in 2008 too, and eventually recovered.” But 2008 didn’t have global lockdowns. No cities of ten million people becoming ghost towns overnight. No cruise ships turning into floating virus incubators, no masks becoming national strategic resources.
This does not mean every analytical tool failed. During upheaval, I need to ask whether a tool’s assumptions still hold, what it can explain, and what falls outside its scope.
Popper’s Reminder
During that period, I revisited the work of philosopher of science Karl Popper.
In Science: Conjectures and Refutations, Popper’s distinction is that an empirical scientific claim must be capable of conflicting with possible observations, with refutation conditions specified in advance. Surviving rigorous tests can give provisional support. This does not make everything outside science meaningless, nor does admitting possible error itself complete a test.
I found this line of thinking particularly powerful when applied to investment and decision-making.
Some investors, myself included, can spend too much time seeking evidence for “why I’m right.” We look for data supporting our views, listen to analysts who agree with us, and seek comfort in echo chambers on social media. The essence of these behaviors is “verification” rather than “falsification.”
I extend the reminder into decisions: alongside supporting data, specify which observations would make me revise or abandon a judgment. That is my application, not a complete scientific test supplied by investment outcomes.
The Power of “I Don’t Know”
Honestly, during those days in March 2020, I did something few people in investment circles are willing to admit: I told myself, I really don’t understand this.
Not false modesty, but genuinely not knowing what would happen next.
I didn’t know how long it would take to develop vaccines. I didn’t know how long lockdowns would last. I didn’t know whether central banks’ massive quantitative easing would trigger inflation, or whether global supply chains would break down.
Each “I don’t know” made me more lucid.
Because the trap of “I know” is this: it makes you act prematurely. Before you truly understand the situation, you make potentially ruinous decisions based on incomplete information. The power of “I don’t know” is this: it makes you wait. Wait for more signals, wait for clearer pictures to emerge.
In running companies, I’ve learned similar lessons. Every day of entrepreneurship is filled with uncertainty, and the most dangerous decisions I’ve witnessed often don’t come from “not knowing what to do,” but from “thinking you know.” Those decisions made with overconfidence, leaving no exit routes, are truly fatal.
Reality Is Always More Brutal Than Models
What happened to that week’s market afterward?
The original article connects this point to later reflection on markets. Subsequent outcomes cannot establish that I already knew the answer in March. Nor can other people’s retrospective claims establish what everyone knew or did not know at the time.
My understanding is that an outcome matching expectations still requires us to examine the original judgment, conditions, and evidence, rather than selecting the result as proof that we were right. This is an extension from my reading, not Popper’s own words about markets.
Reality is always more complex and more brutal than our models. What we can grasp is always just one facet of reality. This isn’t pessimism. It’s cognitive clarity. And in re-examining market judgments and risk preparations, when information floods make us think we can analyze everything, predict everything, this clarity becomes even more precious.
Returning to the March 13 Starting Point
Returning to March 13, 2020 as the starting point, I want to retain caution about my framework: it reveals some things and leaves blind spots still unidentified. Later reflections and the links at the end do not prove that I possessed all that information at the time.
Since then, I’ve maintained greater skepticism toward the word “certainty.” Not avoiding judgment, but leaving a question mark after every judgment.
What I take from this reflection is the habit of checking what I do not know alongside what I feel confident about. And in this era when even AI hallucinates, acknowledging our ignorance may be the most lucid stance of all.
Separating the questions
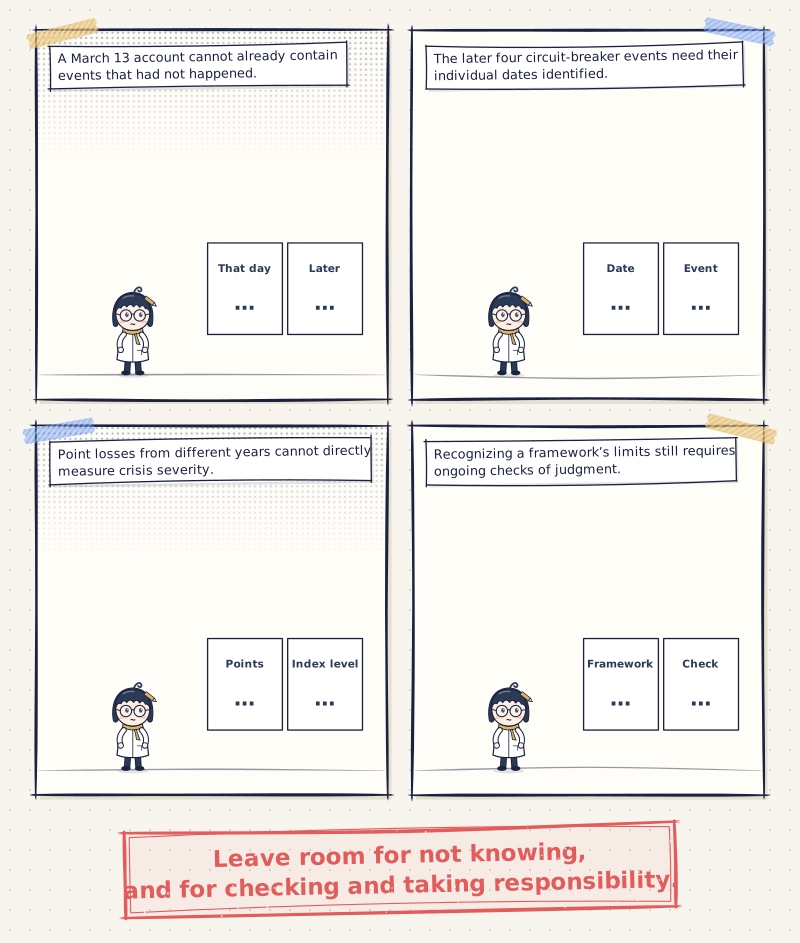
When looking back at markets, mark the date you are standing on.
A March 13 account cannot already contain events that had not happened.
The later four circuit-breaker events need their individual dates identified.
Point losses from different years cannot directly measure crisis severity.
Recognizing a framework’s limits still requires ongoing checks of judgment.
Leave room for not knowing, and for checking and taking responsibility.
Revision and source boundaries: November 5, 2026. This revision uses NYSE’s historical account for the four circuit-breaker dates, indicator, and pause duration, and checks Popper’s original excerpt. It does not newly verify exact Dow closes, point-loss rankings, every analyst’s prediction, or private investment records. Removing nonessential comparisons and universal claims does not declare them disproven for lack of a new check. The historical account is not a verification of current trading rules or advice.

💬 Comments
Loading...